Start a Claim
You do not have to start a claim alone. Report the loss to your insurance company as soon as you can, and call us if you want help starting it.
Or text (203) 819-7059.
Need Help Right Now?
If anyone is hurt, call 911 first. Then report the loss to your insurance company, at the claims number on your policy or your auto insurance card.
Call us at (203) 604-0722 and we will help you start it. Telling us is not the same as telling your insurance company, so the insurance company needs to hear about the loss from you directly.
How It Works
- Get everyone safe.
- Safety comes first. Call 911 if someone is injured.
- Report it to your insurance company.
- Do it as soon as you can, because most policies set a time limit for reporting a claim. Have your policy number, name, address and phone number ready.
- Show what happened.
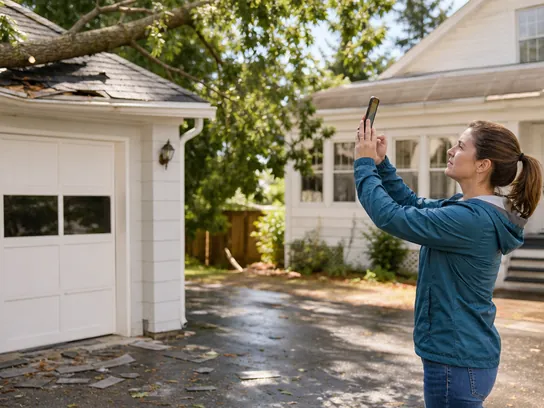
- Take photos and video of the damage and make a list of all the damaged property. You will need that list when you meet the adjuster. Keep receipts for repairs and for new items you buy.
- Call us for help with the first steps.
- You do not have to work out where to begin on your own. Call (203) 604-0722 or text (203) 819-7059.
- Keep a record.
- Write down who you spoke with and when, and ask the adjuster to explain each decision in writing.
By Kind of Loss
- A car accident.
- Make sure everyone is safe and move the car out of traffic if you can do it safely. Exchange information with the other driver, take a photo or sketch of the scene, and ask the officer where to get the accident report and its number. Then call the number on your auto insurance card. If the car was stolen or hit by a driver who left, call the police promptly. See Auto Insurance.
- Water in your home.
- Take photos and video of the damage, and list what was damaged. Water from a leaking pipe is likely covered by a homeowners policy, but ground water from rain, run off or snow melt is not. Sewer or drain backup is an optional add on, and flood is a separate policy. If you carry flood coverage, report the claim within the time your policy sets. See Flood Insurance.
- Storm, wind or hail.
- Photograph the roof, the siding and anything else that was hit, and find out your deductible before you report it. A car damaged by a storm in your garage is usually a claim on the auto policy’s comprehensive coverage, not the homeowners policy. It can help to have your contractor meet with you and the adjuster. See Homeowners Insurance.
- Someone is hurt at your business.
- Report it to your insurance company as soon as you can. General liability insurance protects against financial loss from bodily injury to others, the cost of defending a lawsuit, and settlements or judgments. Keep notes of who you spoke with and when. See General Liability Insurance.
- An employee is hurt on the job.
- Report it to your workers’ compensation insurance company as soon as you can. Workers’ compensation typically covers the employee’s medical expenses, rehabilitation and at least some part of lost wages. See Workers’ Compensation Insurance.
Questions About Claims
Can I talk to a real person about my claim?
Yes. Call (203) 604-0722 or text (203) 819-7059, and we will help you start it. The insurance company still needs to hear about the loss from you directly.
Does telling you report my claim?
No. Telling us is not the same as telling your insurance company. Report the loss to the insurance company as soon as you can, and call us for help with the first steps.
How long do I have to report a claim?
Most policies set a time limit, and the time you have varies by state. Your policy states it, so report the loss as soon as you can.
Will a claim raise my premium?
It can. How often you file and the types of claims you file can affect your auto premium, and your claim history can affect whether your insurer renews your policy. Find out your deductible before you report a smaller loss.
What do I pay before the insurance pays?
Your deductible. You pay it before the insurance company pays a claim, and a lower deductible means a higher premium.
What if I do not agree with the insurance company’s decision?
On a car claim, you do not have to feel rushed or forced to agree, and your insurer does not have the last word. Ask the adjuster to explain the decision in writing. If you disagree about the value, check your policy for an appraisal clause. On a car claim, if you still disagree, your state insurance department’s consumer services staff can help.
Should I hire a public adjuster?
That is your choice. Public adjusters charge fees, so ask about the fee before you decide.
State Facts
In Connecticut
- If you have a question about a claim that you cannot resolve, the Connecticut Insurance Department Consumer Affairs line is (860) 297-3900, and its email address is insurance@ct.gov.
- If you are thinking of hiring a public adjuster, the Insurance Department can confirm whether a public adjuster is licensed.
Already a Client?
Sign in to the Client Center for your policies and documents.
A new flood policy usually takes 30 days to start. The main exception is when it is bought with a new or refinanced mortgage. Do not wait for a storm forecast.
Call When You Are Ready to Start Your Claim.
Your insurance company still needs to hear about the loss from you directly, and we can help with the first steps.