Request a Quote

Commercial Property Insurance

A fire, a windstorm or vandalism can close your doors. Commercial property insurance pays to repair or replace your building, equipment and stock after a covered loss, and you are not left to sort out the claim alone.

Where This Shows Up in Your Day

Where This Shows Up in Your Day

An illustrated building. No people.

  1. 1 of 3

    The Building You Rent Out

  2. 2 of 3

    Water Rises Near Your Building

    Your standard policy does not cover flood, whether you are the landlord or the tenant.

    Ask AboutFlood

    Coverage depends on the policy terms.

    A new flood policy usually takes 30 days to start. The main exception is when it is bought with a new or refinanced mortgage. Do not wait for a storm forecast.

  3. 3 of 3

    Your Lender Sets Requirements

    In a special flood hazard area, a federally regulated lender requires flood insurance.

Why It Matters

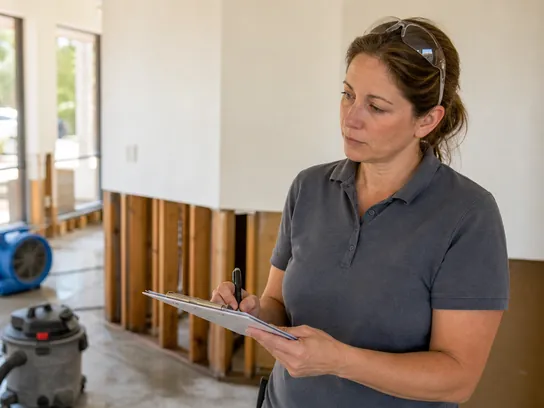
A restoration crew lead in a stripped room, writing on a clipboard beside a drying fan.
  • One fire or windstorm can damage your building, your equipment and your stock at once.
  • Business income cover can keep paying expenses such as payroll while you are closed after a covered loss.
  • A standard business policy does not cover flood, so it pays to know early whether you need a separate flood policy.

Who Needs It

  • Businesses with a significant amount of property and physical assets.
  • Businesses that own a building, or that own equipment, supplies or stock used in the business.
  • Anyone holding customers’ property, such as items left for repair.

What Does Commercial Property Insurance Cover?

Commercial property insurance protects the physical things your business owns and uses, from causes such as fire, smoke, wind and hail, and vandalism.

Your building.
Covers a building your business owns, with its permanently installed fixtures, machinery and equipment. For example, a kitchen fire scorches the walls and the built in hood of the restaurant you own.
Your business property.
Covers most property on or near your premises that you use in the business, such as computers, raw materials and inventory. For example, smoke from a fire next door ruins the stock on your shelves.
Property of others.
Covers property in your care, custody and control, to the extent you are legally liable for it. For example, a fire damages the bikes customers left at your repair shop.
Lost income while you are closed.
Business income coverage, which a business owner’s policy includes, pays the net income you lose, continuing expenses such as payroll, and extra costs to reopen sooner. For example, a fire closes your shop for two months while it is rebuilt.

What a policy covers comes down to its wording, including what it excludes and the conditions it sets.
What Commercial Property Insurance Does Not Cover

Property insurance is built for sudden, accidental damage. These are left out of a standard policy, or need cover of their own.

Flood.
Standard business policies do not cover flood. Flood is a separate policy from the National Flood Insurance Program or a private insurer. See flood insurance.
Earthquake.
Earthquake is generally not covered. A separate policy is available.
Wear and tear.
Gradual aging is not accidental, so it is not covered.
Power failure and temperature changes.
A power failure is usually excluded from a basic business owners policy, except damage to computers and electronic data, and so are changes in humidity or temperature. Spoilage cover can be added for goods that must stay cold.
Your vehicles.
Vehicles subject to motor vehicle registration are usually excluded. They belong on commercial auto insurance.
Equipment that travels.
Tools and machinery that move from job to job need a floater, not standard property insurance.
A shutdown caused by someone else’s loss.
Business income pays only after a direct loss to your property from a covered cause.

How Much Does Commercial Property Insurance Cost?

There is no single price. The premium follows your building, how broad the cover is and your record, and these are the factors an insurer weighs:

The building.
Its square footage and its type of construction.
How broad the cover is.
Open perils cover, which lists only what it excludes, costs more than cover for named perils only.
Your claims record.
A good record generally brings more insurers to compete for your business.
Your deductible.
The higher the deductible, the lower the premium.
Your risk control.
Businesses that invest in preventing losses have fewer claims on average.

To start a quote, tell us what you own and where it sits.

How Much Coverage Do You Need?

Insure to value.
The limit should be the estimated amount needed to rebuild your building.
Replacement cost or actual cash value.
Replacement cost pays to replace with new construction. Actual cash value pays what the property is worth.
Coinsurance.
A building insured for less than its value can face a penalty at the time of a loss. Agreed value cover waives that penalty.
Flood limits.
National Flood Insurance Program building coverage tops out at $500,000 for non residential buildings, and contents coverage at $500,000 for non residential property.

Coverage by Industry

Your building, your stock and your equipment are what this policy protects. These are some of the businesses that carry it:

State Facts

In Connecticut

  • Under Public Act 25-33, homeowners, renters, dwelling fire and condo policies effective on or after July 1, 2026 must carry a clear notice that flood is not covered. This is a personal and dwelling fire rule; a standard business policy does not cover flood either.
  • Inland flooding, sewer backup, groundwater seepage and sump pump failure are named Connecticut flood risks, not only coastal storms.

Source: Connecticut Insurance Department.

Insurance in Connecticut

Frequently Asked Questions

What does commercial property insurance cover?

It protects company property from events including fire, smoke, wind and hail, and vandalism. The policy wording determines what applies to a particular loss.

Does commercial property insurance cover flood?

No. Standard business policies do not cover flood. Flood is a separate policy from the National Flood Insurance Program or a private insurer.

Does commercial property insurance cover earthquake?

Earthquake is generally not covered. A separate policy is available.

Does it pay my lost income if I have to close after a fire?

Business income coverage pays the net income you lose and continuing expenses such as payroll, after a direct loss from a covered cause. A business owner’s policy includes it.

How much flood coverage can a commercial building obtain from the National Flood Insurance Program?

Building coverage tops out at $500,000 for non residential buildings, and contents coverage tops out at $500,000 for non residential property. Private flood insurers also sell policies.

Will my lender require flood insurance?

Federally regulated lenders may not make, increase, extend or renew a loan on a building in a special flood hazard area unless it carries flood insurance.

Do I need commercial property insurance if I rent my space?

That depends on what you own inside the space. The SBA lists it for businesses with a significant amount of property and physical assets. Put what you own inside the space beside the insurance requirements in your lease, and ask which coverage fits.

Get Property Coverage That Fits Your Building.

Tell us what you own, where it sits and the date you need coverage to start, and send the policy you have now if there is one. The full range of business coverage is on the Business Insurance page.